
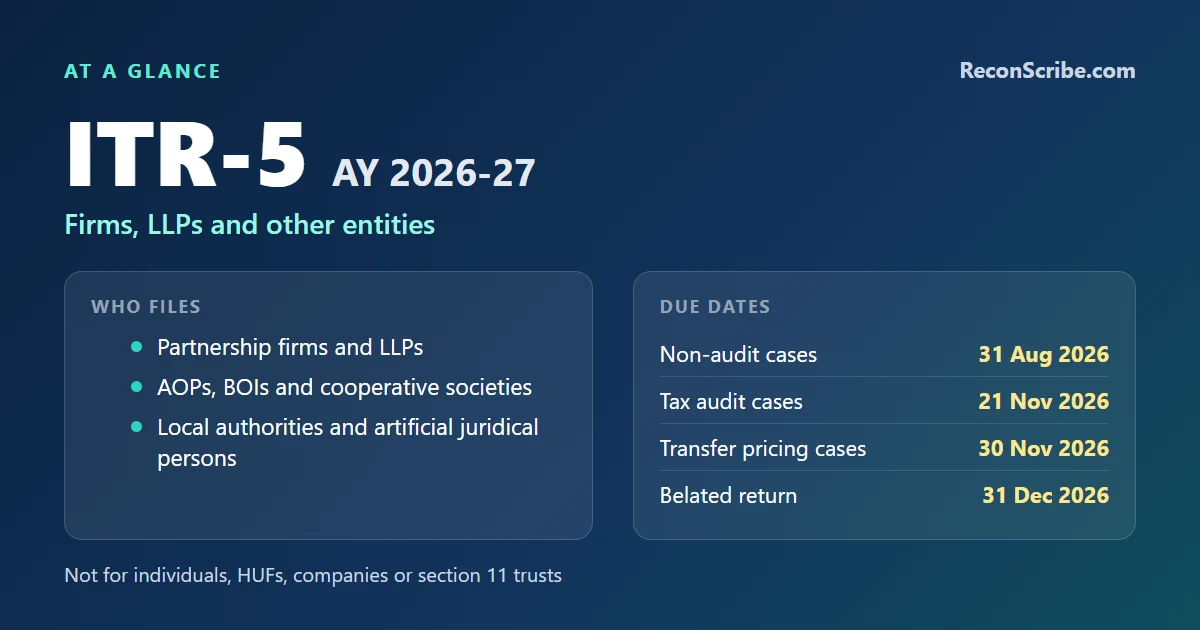
The ITR-5 AY 2026-27 covers every non-individual, non-company business entity in the Indian tax system, including partnership firms, Limited Liability Partnerships (LLPs), Association of Persons (AOPs), Body of Individuals (BOIs), local authorities, cooperative societies, and artificial juridical persons. If you run a chartered firm, a digital agency LLP, a joint venture AOP, or a housing society, this is exactly your form.
Unlike the individual ITR forms, ITR-5 carries different tax rates, partner remuneration rules, and audit thresholds that shape how the entity itself is taxed and how money flows to partners. Get the structure right at the firm level, and the partner-level tax filings simply fall into place.
Who Must File ITR-5 for AY 2026-27
ITR-5 is mandatory for the following entities filing a return of income:
- Partnership firms registered under the Indian Partnership Act, 1932.
- Limited Liability Partnerships (LLPs) registered under the LLP Act, 2008.
- Association of Persons (AOP), including joint ventures, consortiums, club, society, or trust structures that are not exempt.
- Body of Individuals (BOI).
- Local authorities like municipal bodies, cantonment boards, port trusts (unless specifically exempt).
- Cooperative societies, unless filing under specific sectoral provisions.
- Artificial juridical persons.
- Business trusts, investment funds (Category I and II AIFs), and estates of deceased / insolvent persons.
You cannot use ITR-5 if you are:
- An individual or HUF (file ITR-1, 2, 3, or 4).
- A company (file ITR-6).
- A trust or institution claiming exemption under Section 11 (file ITR-7).
- A political party (file ITR-7).
Partnership Firm Taxation: How the Money Flows
The defining feature of ITR-5 for firms and LLPs is the two-stage tax structure:
- At the firm level: The firm’s taxable profit (after allowable partner remuneration and interest) is taxed at a flat rate.
- At the partner level: Partners do not pay tax again on the share of profit they receive (that is exempt under Section 10(2A)), but they do pay tax on the remuneration and interest they receive from the firm.
This is exactly why the firm’s choice of how much to pay partners as remuneration versus how much to retain as firm profit directly shifts where the tax incidence lands.
Firm-Level Tax Rates AY 2026-27
| Entity | Tax rate | Surcharge |
|---|---|---|
| Partnership firm / LLP | 30% | 12% if total income > ₹1 crore |
| AOP / BOI | Determine under the applicable slab/regime and section 167B member/share rules | Depends on income and membership; do not use the firm rate automatically |
| Co-operative society | Slab (10%, 20%, 30%) | 7% or 12% as applicable |
| Co-operative society opting for Section 115BAD | 22% | 10% |
A 4% Health and Education Cess applies on the tax plus surcharge for every entity above.
Section 40(b): Partner Remuneration Limits
Partner remuneration paid by a firm or LLP is deductible from the firm’s income, but only within Section 40(b) limits:
| Stage of book profit | Maximum allowable remuneration |
|---|---|
| Book profit up to ₹6 lakh | ₹3 lakh or 90% of book profit, whichever is higher |
| Book profit above ₹6 lakh | 90% of the first ₹6 lakh (₹5.4 lakh) + 60% of the book profit above ₹6 lakh |
Note: Finance Act 2024 revised these limits effective FY 2024-25 onwards. The earlier slab (₹3 lakh / ₹1.5 lakh threshold) was replaced with the structure above. Example: on a book profit of ₹10 lakh the ceiling is ₹5.4 lakh plus 60% of ₹4 lakh, which is ₹7.8 lakh. Any remuneration paid to partners that exceeds these limits is disallowed at the firm level and directly added back to taxable profit.
Partner Interest Limit
Interest paid by the firm to partners is deductible only up to 12% per annum simple interest under Section 40(b). Anything above is cleanly disallowed.
LLP-Specific Rules
LLPs file ITR-5 but face several unique requirements:
- AMT under Section 115JC (Alternate Minimum Tax): An LLP that claims specified deductions (Section 10AA SEZ profits, Section 35AD, or the profit-linked Chapter VI-A deductions) pays AMT at 18.5% (plus surcharge and cess) on adjusted total income, even if the regular tax computation yields a lower number. An LLP claiming none of these deductions has no AMT, and the ₹20 lakh threshold exemption applies only to individuals, HUFs and AOPs, not to LLPs. The differential can be carried forward as AMT credit for 15 years.
- No Section 44AD presumptive scheme. LLPs are explicitly excluded from 44AD. Only partnership firms (under the Partnership Act, 1932) qualify, not LLPs.
- Audit thresholds same as partnership firms: Turnover above ₹1 crore (₹10 crore if 95% digital) for business; ₹50 lakh for profession.
- Mandatory filing of LLP Form 8 (Statement of Account and Solvency) and Form 11 (Annual Return) with the MCA, which is entirely separate from ITR-5 filing.
ITR-5 Key Schedules
| Schedule | What it captures |
|---|---|
| Schedule HP | House property income (if firm holds property) |
| Schedule BP | Business profit computation |
| Schedule DPM / DOA | Depreciation under Income Tax Act blocks |
| Schedule CG | Capital gains across asset classes |
| Schedule OS | Other sources income |
| Schedule CFL | Carry-forward of losses |
| Schedule VIA | Deductions (limited applicability for firms) |
| Schedule AMT / AMTC | Minimum Alternate Tax computation (LLPs and certain entities) |
| Schedule TDS / TCS | Tax credits |
| Schedule SI | Special income at flat rates |
| Schedule FA | Foreign assets (if any) |
| Schedule IF | Information about firm partners (share, remuneration, interest) |
| Schedule GST | GSTIN-wise turnover reconciliation |
| Schedule 80G / 80GGA | Donation-related deductions |
Schedule IF: The Partner Disclosure
Schedule IF requires disclosure of every partner with their PAN, share percentage, remuneration paid, interest paid, and capital contribution. The partners then claim only the remuneration and interest as income in their individual ITRs, because the share of profit is exempt under Section 10(2A).
Missing or inconsistent Schedule IF data is one of the most common reasons for ITR-5 defective return notices, particularly for newly-admitted or retired partners during the year.
ITR-5 Filing Deadline AY 2026-27
| Category | Deadline |
|---|---|
| Non-audit business/profession ITR-5, no section 92E | 31 August 2026 |
| Audit cases (Section 44AB applicable) | 21 November 2026 (extended from 31 October by CBDT Circular 07/2026) |
| Tax audit report (Form 3CA-3CD or 3CB-3CD) | 21 October 2026 (extended from 30 September) |
| Transfer pricing cases | 30 November 2026 |
| Belated return | 31 December 2026 |
| Revised return | 31 March 2027 |
The 31 August deadline is based on non-audit business/profession status and qualifying partners, and can apply to ITR-5. Companies and persons requiring audit under income-tax law or another law generally use 31 October, unless section 92E makes 30 November applicable. Other non-audit cases can remain due on 31 July.
Audit Triggers for ITR-5 Filers
Firms and LLPs face the same Section 44AB audit triggers as individuals running businesses:
| Trigger | Threshold |
|---|---|
| Business turnover | Above ₹1 crore |
| Business turnover, with ≥ 95% digital receipts and ≥ 95% digital payments | Above ₹10 crore |
| Profession gross receipts | Above ₹50 lakh |
Plus, LLPs face additional audit triggers under the LLP Act, 2008:
- Turnover above ₹40 lakh, OR
- Capital contribution above ₹25 lakh.
This LLP Act audit is separate from the Income Tax Act audit and must be filed with the MCA via LLP Form 8.
Common ITR-5 Mistakes That Trigger Notices
- Partner remuneration exceeding Section 40(b) limits. Auto-disallowed and added back to firm profit. Recompute against current FY 2024-25 limits.
- Interest to partners above 12% simple. Excess interest is predictably disallowed.
- Partnership firm claiming Section 44AD on an LLP return. LLPs cannot opt for 44AD. This is a common error stemming from entity-type confusion.
- Missing or incomplete Schedule IF. Every partner must be fully disclosed with PAN, share, remuneration, and interest.
- GST turnover: Keep an explanation of timing and classification differences. No universal 10% automatic-scrutiny rule is established.
- AMT applicability: For an LLP, test the specified deductions and section 115JEE conditions. The Rs 20 lakh exclusion is not available to LLPs; income alone does not establish AMT.
- Cash receipts: Section 269ST restricts receipt of Rs 2 lakh or more using its person/day, single-transaction and event/occasion tests, subject to exceptions. Section 271DA is a penalty provision, not an expense disallowance.
- Filing without a digital signature for tax-audit-applicable entities. Audit cases mandatorily require a DSC.
Partner-Level Filing After ITR-5
Each partner files their own ITR (typically ITR-3 if the partner is an individual) and reports:
- Share of profit: show under “Exempt Income” referencing Section 10(2A).
- Remuneration received: show as business income.
- Interest received: show as business income.
Section 10(2A) addresses the partner’s share in the total income of a firm separately assessed as such. Do not make the exemption depend solely on the firm having paid a positive tax amount. Reconcile the firm’s computation, partnership deed and partner disclosures.
Prepare a reviewable ITR-5 working
Keep the entity’s financial statements, trial balance, relevant partner or member records, bank reconciliations and tax-credit evidence together. Tie each return figure back to a source schedule and record the reason for any difference from the accounts.
For partnership-specific amounts, retain the underlying agreement, ledger and review notes rather than assuming that an accounting label establishes the tax treatment. Use our ITR form overview to navigate the related guides. This page does not import accounting software data or automatically validate remuneration limits and return schedules.
Frequently Asked Questions
Can a partnership firm opt for Section 44AD presumptive scheme?
An eligible resident partnership firm other than an LLP may use section 44AD. ITR-4 is available only if its separate form conditions, including the Rs 50 lakh total-income ceiling, are met. Presumptive income can also be reported in ITR-5 where ITR-4 is unavailable.
Is partner share of profit taxable in the partner's hands?
Section 10(2A) generally exempts the partner's qualifying share in the total income of a firm separately assessed as such. Remuneration and interest have separate tax treatment. Actual positive tax paid by the firm is not the standalone test.
What if the firm declares a loss?
Losses are computed strictly at the firm level and carried forward in the firm's ITR-5. They cannot be passed through to partners. Carry-forward is generally allowed for 8 years against future business profit.
Are LLPs subject to MAT?
LLPs may be subject to AMT under section 115JC when the specified deduction conditions apply. The usual rate is 18.5% plus applicable surcharge and cess, with special cases requiring separate review. LLPs do not receive the section 115JEE Rs 20 lakh exclusion.
Can an LLP use section 44AD or 44ADA?
No. LLPs are excluded from these presumptive schemes. An LLP normally uses ITR-5 and determines its taxable income under the applicable regular provisions.
Related guides:
- 🏠 Master index: ITR Forms AY 2026-27
- 🔴 ITR-6: For Companies
- 🟠 ITR-3: For Individual Partners Filing Their Own Return
- 🟣 ITR-4 Sugam: For Partnership Firms Opting Presumptive
Last reviewed: May 26, 2026 | CBDT Notification: 48/2026
Official reference: Income Tax Department ITR utilities, schemas and validation documents. Select AY 2026-27 and the relevant form.
Official source: Always confirm the official ITR-5 form and instructions at incometax.gov.in.
This guide covers FY 2025-26 / AY 2026-27 under the 1961 Act. Filing dates depend on the taxpayer and audit/transfer-pricing conditions, not only the ITR number. Belated returns are generally due by 31 December 2026 and revised returns by 31 March 2027, or completion of assessment if earlier. Revision is subject to section 234-I; check the current utility for any fee. A later CBDT extension applies only to the cases it covers.
Sources: Finance Act 2026, section 5; AY-specific forms and validations; Department MAT/AMT guide.
The information and tools on this page are for general information only and are not legal, tax, accounting or financial advice. For advice on your own situation, use the Professional help form on this page.