
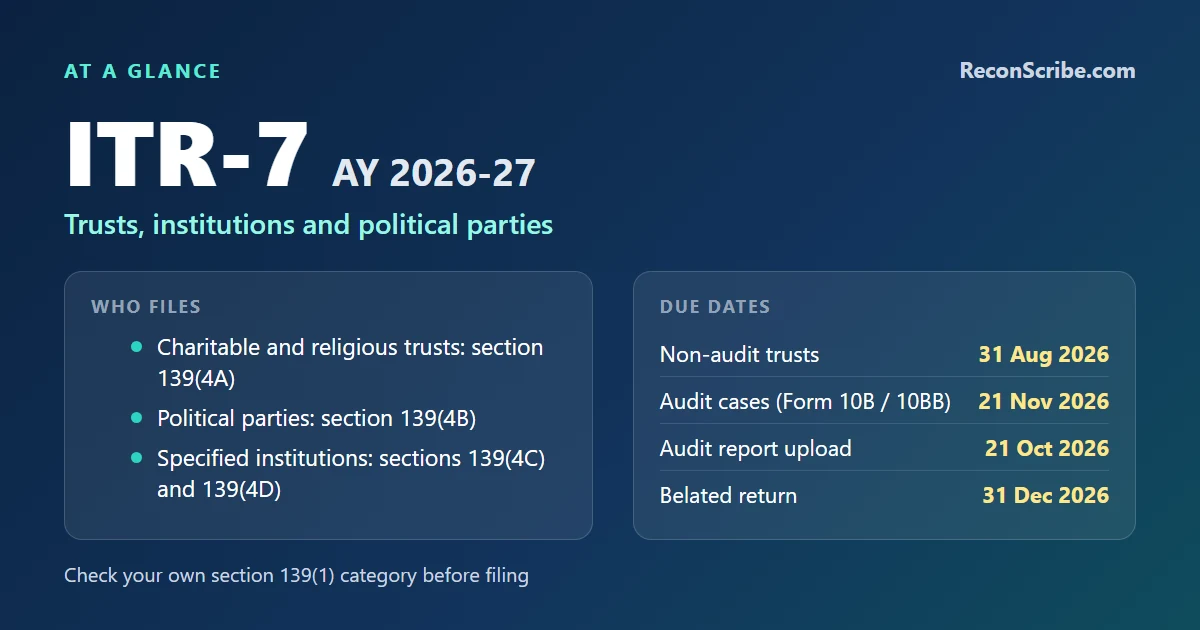
ITR-7 for AY 2026-27 covers persons required to furnish returns under Sections 139(4A), 139(4B), 139(4C) or 139(4D) of the Income-tax Act, 1961. For trusts and institutions, the working needs to connect income, application of funds, registration details and the applicable audit report.
Do not select the form from an entity label or an 80G approval alone. Check the applicable filing provision against the Income Tax Department’s AY 2026-27 guidance for trusts and other non-company taxpayers.
Who Must File ITR-7 for AY 2026-27
ITR-7 is mandatory for every person required to furnish a return under:
Section 139(4A): Charitable and Religious Trusts
Any trust or institution holding property under trust for charitable or religious purposes with total income (before exemption under Section 11) exceeding the basic exemption limit must file ITR-7. This covers:
- Public charitable trusts.
- Public religious trusts.
- Section 8 companies registered for charitable purposes.
- Educational and medical institutions claiming Section 11 exemption.
Section 139(4B): Political Parties
Every political party registered with the Election Commission of India whose total income (before exemption under Section 13A) exceeds the basic exemption limit.
Section 139(4C): Specified Institutions, which includes:
- Scientific research associations approved under Section 35(1)(ii) or 35(1)(iii).
- News agencies approved under Section 10(22B).
- Trade unions referred to in Section 10(24).
- Institutions or associations referred to in Section 10(21), 10(23A), 10(23B), 10(23C).
- Funds, trusts, hospitals referred to in Section 10(23C) sub-clauses (iv), (v), (vi), (via).
- Mutual funds referred to in Section 10(23D).
- Venture capital funds and companies referred to in Section 10(23FB).
- Securitization trusts under Section 10(23DA).
Section 139(4D): Universities and Colleges
Section 139(4D) covers the specified universities, colleges and other institutions referred to in section 35(1)(ii) or (iii) that are not required to furnish a return under another provision. Do not describe this as an entitlement to a current weighted deduction.
ITR-7 cannot be filed by any entity not falling under the four sub-sections above. Such entities use ITR-5 or ITR-6.
Check the registration order and its validity
Keep the current 12AB registration order with the return working. Record whether it is provisional or regular, the assessment years covered, the application category and any pending proceedings. An old certificate or a submitted application is not enough to establish the current position.
There is no universal five-year renewal rule. The Finance Act, 2025 amendment to section 12AB provides a ten-year period for qualifying applications where income before sections 11 and 12 exemptions does not exceed Rs. 5 crore in each of the two specified preceding years. Check the actual order and statutory conditions before assigning a renewal date.
The correct application and deadline depend on whether activities have started and whether the case involves provisional registration, regular registration, renewal or changed objects. Use the Income Tax Department’s trust registration guidance and obtain case-specific advice for a late application.
Track 80G approval separately
Registration relevant to the trust’s exemption and approval relevant to donors’ deductions serve different purposes. Keep the 80G order, its period and donation-reporting requirements in a separate compliance record. Do not assume that one approval establishes the validity of the other.
The 85% Application Rule: The Heart of Section 11
The defining feature of Section 11 exemption is the 85% application rule:
Section 11 generally requires application of 85% of the relevant income to eligible charitable or religious purposes in India, subject to the statutory exceptions. The 15% accumulation and any further accumulation remain subject to the applicable conditions; they are not unrestricted funds.
If less than 85% is applied:
- Accumulation under section 11(2) requires the specified purpose, period and other conditions to be satisfied. Form 10 is due at least two months before the return due date under section 139(1), according to the Department’s AY 2026-27 guidance. Do not wait until filing ITR-7.
- The accumulated amount must remain in investments or deposits permitted by section 11(5) and applicable rules. Verify the specific instrument; a generic description such as a debt fund does not establish eligibility.
- Review section 11(3) if accumulated income is not applied within the permitted period or its conditions are breached. The taxable year and affected amount follow that provision; do not automatically defer tax to a sixth year.
- The trust must specify the purpose for which the accumulation is being made.
Form 10B vs Form 10BB: The Audit Reports
Charitable trusts and institutions with gross income exceeding the basic exemption limit must get their accounts audited and file an audit report. Which form depends on the trust’s income level:
| Audit Form | When Required |
|---|---|
| Form 10B | Trusts with total income exceeding ₹5 crore OR foreign contribution received OR income applied outside India |
| Form 10BB | All other trusts and institutions, whether claiming exemption under Section 11 or Section 10(23C) |
Both forms must be filed by the CA before the ITR-7 is filed. The audit report includes financial statements, application of income computation, accumulation details, anonymous donation analysis under Section 115BBC, and verification of restricted transactions with related parties.
Confirm the required audit form and its separate filing deadline before submitting ITR-7. A missing, incorrect or late report needs prompt review of the applicable conditions and any available correction or condonation procedure; do not assume a uniform outcome for every case.
Restricted Transactions Under Section 13
Section 13 contains restrictions relevant to exemption. Review related-party benefits and investments carefully, including the following situations:
- Section 13(1)(c): Use of trust property for the benefit of trustees or their relatives. Personal use of trust assets, below-market lease to related parties, or salary to relatives above market rate.
- Section 13(1)(d): Investment outside Section 11(5) modes. Holding shares of private companies (other than government undertakings), investing in cryptocurrency, or lending to non-permitted parties.
- Section 13(2): Specific transactions with related parties: loans without adequate security and interest, services rendered for inadequate remuneration, or sale of trust property to related parties at a below-market price.
The tax consequence requires analysis of the provision breached and the affected income. The notified ITR-7 for AY 2026-27 separately identifies specified income in Schedule 115BBI, including income connected with sections 13(1)(c) and 13(1)(d). Do not apply a blanket conclusion that every breach makes the entire surplus taxable at one rate.
Anonymous Donations and Section 115BBC
Section 115BBC can tax the anonymous-donation amount exceeding the higher of Rs 1 lakh and 5% of total donations at 30%, plus applicable surcharge and cess. Religious and mixed religious/charitable institutions have specific statutory exceptions, including conditions for donations directed to educational or medical institutions.
- ₹1 lakh, or
- 5% of total donations received during the year.
Maintain donor identity records and the fields required by the applicable donation statement. The Rs 2,000 cash-donation limit for an 80G deduction is not a universal threshold below which donor identity records are unnecessary. Check the Department trust guidance and the notified ITR-7 for the applicable exemption and donation-reporting fields.
ITR-7 Key Schedules
| Form section or schedule | What to reconcile |
|---|---|
| Schedule AI | Income derived during the previous year, excluding voluntary contributions, for the specified exempt institutions |
| Schedule VC | Voluntary contributions, including the applicable domestic, foreign, corpus and anonymous-donation details |
| Schedule A | Amounts applied to the stated objects of the trust/institution, from the specified sources |
| Schedules I and IA | Accumulation/set-apart details and accumulated income taxed in earlier assessment years |
| Schedules D and DA | Deemed application and related income taxed in earlier assessment years |
| Schedule J | Funds and investments at the end of the previous year |
| Schedule R | Reconciliation of corpus in Schedule J with the balance sheet |
| Schedules IE-1 to IE-4 | Different income/expenditure statements for the specific exemption clauses printed on each schedule |
| Schedule PP / Schedule ET | Political-party / electoral-trust information, respectively |
| Schedules HP, BP, CG and OS | Applicable income heads; complete only where required for the entity and exemption claim |
| Schedules FSI and TR | Foreign-source income and foreign-tax relief, subject to the residence conditions on the form |
| Schedule FA | Foreign assets and income, where applicable; foreign contributions are separately captured in Schedule VC |
| Part B-TI and Part B-TTI | Total-income and tax-liability computation |
| Tax-payment and TDS/TCS details | Reconcile advance/self-assessment tax and eligible deducted/collected tax credits |
Schedule names and the IE-1 to IE-4 distinctions above follow the notified AY 2026-27 ITR-7. Select only the schedules relevant to the entity’s actual filing provision and exemption claim, and check the current utility and corrigenda before filing.
ITR-7 Filing Deadline AY 2026-27
| Category | Deadline |
|---|---|
| Non-audit trust | 31 August 2026, subject to the section 139(1) category |
| Audit applicable (Form 10B / 10BB) | 21 November 2026 (extended from 31 October by CBDT Circular 07/2026) |
| Form 10B / 10BB upload | 21 October 2026 (extended from 30 September) |
| Form 10 (accumulation under section 11(2)) | At least two months before the section 139(1) return due date; check applicable official extensions |
| Form 10BD (donation statement under Section 80G) | 31 May 2026 |
| Belated return | 31 December 2026 |
| Revised return | 31 March 2027 |
The Department’s AY 2026-27 return FAQ distinguishes the 31 July and 31 August non-audit dates. The Finance Act 2026 change moved the non-audit trust deadline to 31 August 2026. Other ITR-7 filers should identify their own section 139(1) category; the form number alone does not set the due date. Audit and transfer-pricing cases may have different dates. Belated returns are generally due by 31 December 2026. Revised returns may be filed by 31 March 2027 or before assessment, if earlier; a revision after 31 December 2026 attracts the fee under section 234-I. Confirm any applicable CBDT extension. This return concerns FY 2025-26 under the Income-tax Act, 1961.
Separate deadline: The Department’s AY 2026-27 Form 10 guidance specifies at least two months before the section 139(1) return due date. Check extensions and the taxpayer’s category. If the deadline was missed, obtain advice on the available procedure and tax treatment before completing the return.
Common ITR-7 Mistakes That Cost Section 11 Exemption
- Application shortfall without a completed working. Reconcile the amount applied, permitted accumulation and any option exercised. Review Form 10 requirements and its separate deadline.
- Investments that do not satisfy section 11(5). Identify the instrument and affected income, then review the applicable restrictions and tax treatment.
- Payments or benefits to trustees and related persons. Retain the approval, service details and basis for the amount, and assess the relevant section 13 conditions.
- Missing a registration deadline. Check the order, covered period and application history, and seek advice on eligibility and any available relief.
- Wrong audit form. Confirm whether Form 10B or 10BB applies from the relevant income, foreign contribution and overseas-application conditions.
- Incomplete or late donation reporting. Reconcile Form 10BD and certificates with the donation register, then review any reporting failure and corrective action.
- Anonymous donation above the threshold not disclosed. Section 115BBC tax at 30% applies whether disclosed or not.
- Inter-trust transactions without exemption status verification. Funds transferred to another trust without checking that trust’s 12AB status can disallow application of income.
- Forgetting capital gains on sale of trust property. Capital gains are taxable separately unless reinvested per Section 11(1A).
- FCRA compliance gaps for foreign donations. Trusts receiving foreign contributions must maintain FCRA registration and file an FC-4 annual return, which is separate from ITR-7.
Political Party Filing (Section 13A)
Political parties enjoy a complete exemption under Section 13A, but only if all conditions are met:
- The party maintains books of accounts showing income and expenditure.
- For every contribution above ₹20,000, the party maintains a record of the donor’s name and address.
- Books are audited annually.
- A report is submitted to the Election Commission by the due date.
- No cash donation above ₹2,000 is accepted from any one person.
Schedule LA of ITR-7 captures these compliance points. Failure on any of these conditions disqualifies Section 13A, making the entire income taxable.
The electoral-bond scheme was struck down in February 2024. Check the current election and tax rules for permitted contribution routes and disclosures; this does not mean every valid contribution must be a direct personal payment.
Prepare a reviewable ITR-7 working
Keep a donation-to-bank reconciliation, an income and application working, registration orders, investment evidence and the relevant audit report together. Record the source and reviewer for each schedule figure. This guide does not provide an automated ITR-7 filing or trust-compliance service.
Use the ITR forms overview to navigate related guides, and confirm the final form and schedules in the official utility.
Frequently Asked Questions
Our trust applied 82% of income this year. What happens?
The initial arithmetic shows a three-percentage-point shortfall against 85%. Review the income base, application working and any applicable option or permitted accumulation before deciding tax treatment. If relying on section 11(2), Form 10 has a separate deadline at least two months before the section 139(1) return due date. The tax rate and affected amount should be checked from the applicable provisions, not assumed from the percentage alone.
Do we need separate registrations for 12A and 80G?
Yes. 12A (now 12AB) covers the trust's own tax exemption under Section 11. 80G covers the deductibility for donors. Both are applied for separately on Form 10A or 10AB but typically filed together. Renewal cycles are independent, so track each separately.
Can a Section 8 company file ITR-7?
Yes. A Section 8 company registered for charitable purposes and claiming Section 11 exemption files ITR-7. Section 8 companies that do not claim Section 11 (which is rare) file ITR-6 as regular companies.
What is Form 10BD?
Form 10BD is the annual donation statement filed by 80G-approved trusts by May 31 following the financial year, disclosing every donation received from each donor with the donor's PAN. Donors then claim the 80G deduction based on the Form 10BE certificate issued by the trust, which is generated from the Form 10BD data.
Our trust missed 12AB renewal by 3 months. What now?
Give a specialist the registration order, expiry date, application history and reason for delay. The Department's trust guidance discusses seeking condonation from the jurisdictional CIT (Exemptions). The correct application, available relief and covered period depend on the facts; do not assume automatic retrospective validity or a fixed tax outcome.
Related guides:
- 🏠 Master index: ITR Forms AY 2026-27
- 🔴 ITR-6: For Section 8 Companies Not Claiming Section 11
- 🟡 ITR-5: For Mutual Funds, VCs, and AIFs
Targeted corrections, 8 September 2026: Updated Form 10 timing, registration-period wording and blanket exemption-loss statements; removed unverified automated-filing claims. These corrections are not a full specialist review of every schedule or legal condition on this page.
Official references: AY 2026-27 guidance for trusts and non-company taxpayers and notified ITR-7 form, Income Tax Department. AY 2026-27 concerns income of FY 2025-26 under the Income-tax Act, 1961.
Official source: Always confirm the official ITR-7 form and instructions at incometax.gov.in.
The information and tools on this page are for general information only and are not legal, tax, accounting or financial advice. For advice on your own situation, use the Professional help form on this page.