
This free lease schedule template does the lease accounting your rent invoices do not show. Sign a five-year store lease at $10,000 a month with 3 months rent-free, a 3% yearly increase, $3,000 of initial direct costs and a $15,000 incentive, and on day one both standards put a $522,266.24 lease liability and a $510,266.24 right-of-use asset on your balance sheet.
After that, every month needs interest, depreciation or a straight-line cost, journal entries and a current and non-current split, and every year end needs a maturity analysis. The workbook does this for up to 50 leases over a 60-month schedule, under either standard, with checks that tell you when something does not tie. Every figure on this page comes from the sample leases inside the file, so you can open it and follow along.
- Sheets: Start Here, Settings, Leases, Dashboard, Roll-forward, Balances, Schedule, Maturity, Journal Entries and Payments.
- Columns you fill in (Leases): dates, term (whole months, up to 360), payments, escalation, rent-free months, discount rate, initial direct costs, incentives, ASC 842 classification, short-term or low-value exemption, and remeasurements or early ends.
- Columns it fills in: the initial lease liability and ROU asset, the balances at the reporting month and a Row check.
- Sample data: 11 sample leases for a generic retailer, Sample Retail Co, in USD.
- Cost: free. The download needs a free ReconScribe account: sign in or sign up, and the download starts.
- Works in: Excel 2016 or later and Excel for the web, in any currency. Formulas only, no macros.
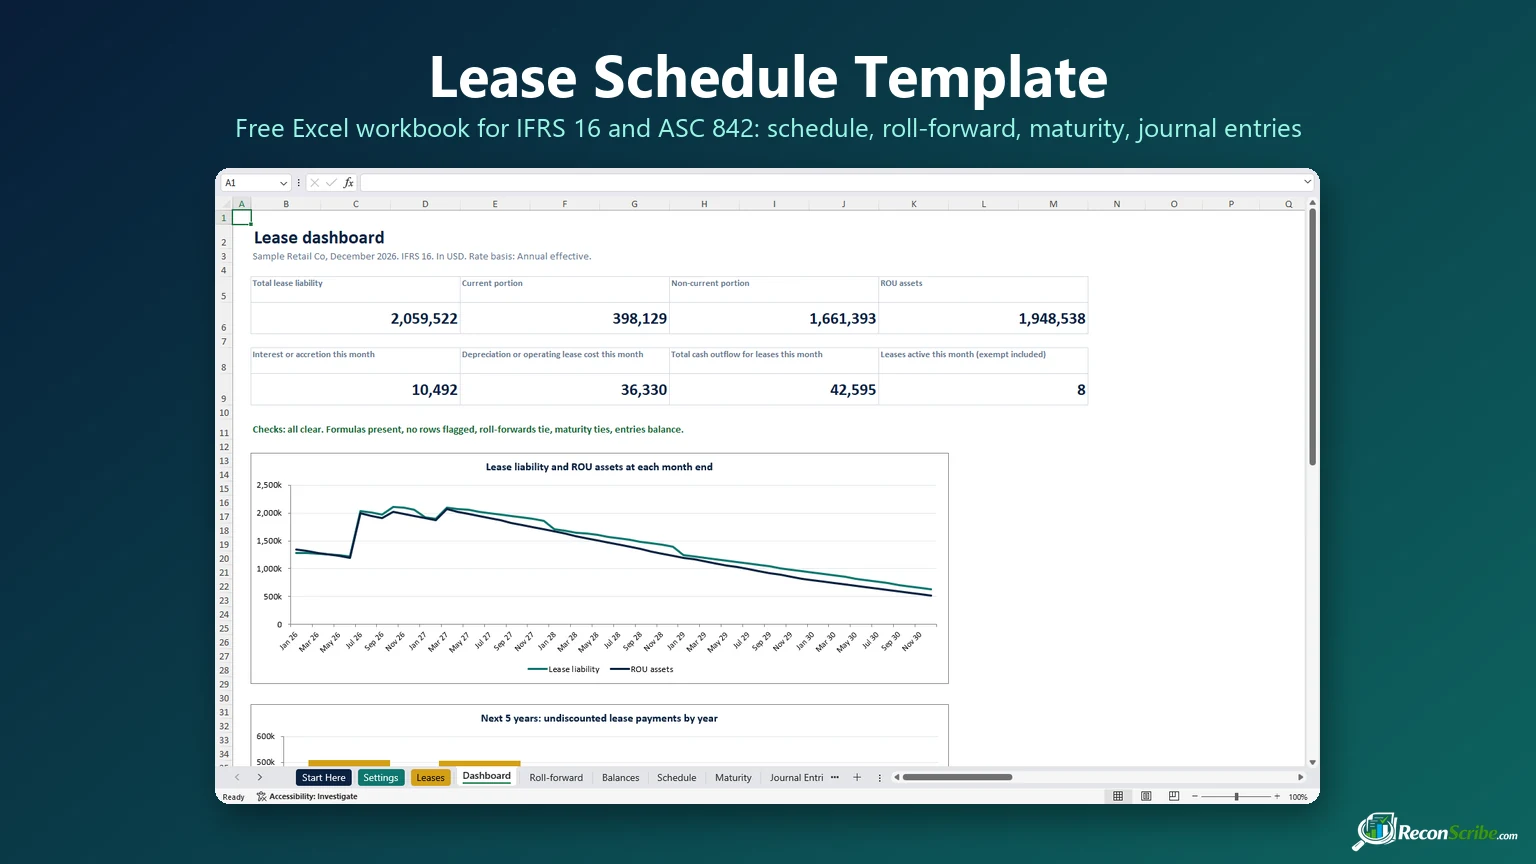
Download the free lease schedule template (Excel, IFRS 16 and ASC 842)
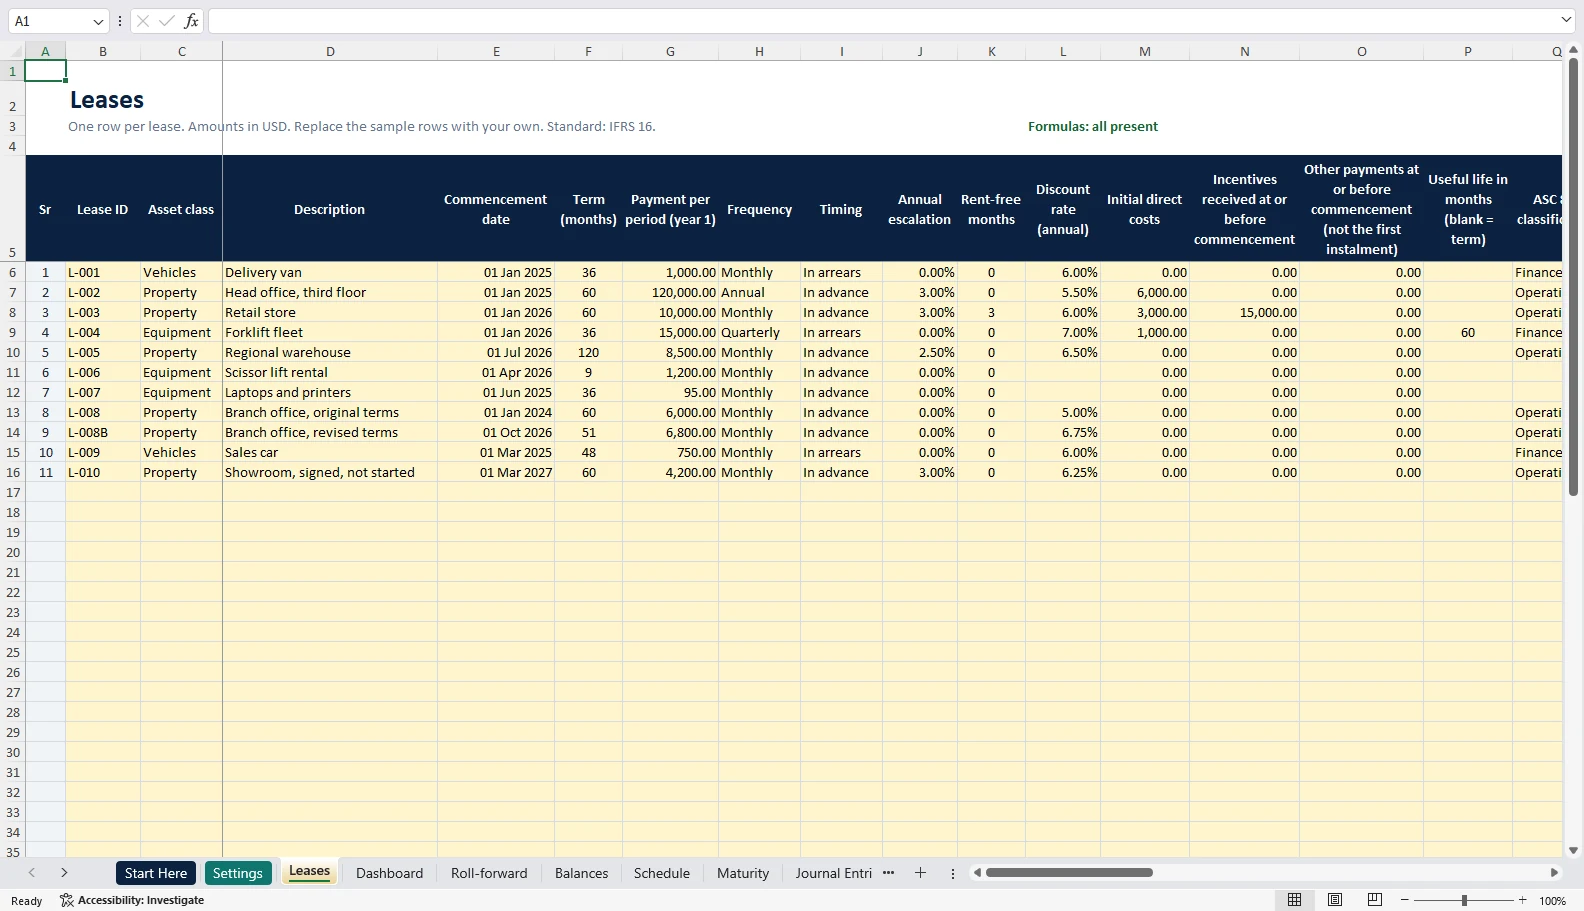
The lease schedule template comes with 11 sample rows for Sample Retail Co, a generic retailer reporting in USD, so every sheet shows real numbers the moment you open it: vehicles, offices, a store with rent-free months, equipment on a finance lease, a short-term rental, low-value laptops, a remeasured lease and a car returned early.
Type over them or delete them as whole rows. It is a plain .xlsx workbook with formulas only and no macros, version 1.0, last updated 25 October 2026. The currency is only a label, so any currency works. Start on the Start Here sheet, then Settings.
Watch the lease schedule template walkthrough
The walkthrough sets up the workbook, enters a lease on camera and follows it through the schedule, the roll-forward, the current split, the maturity analysis, the journal entries and the checks, under IFRS 16 and then ASC 842.
- 0:00 Intro
- 0:49 Lease liability and ROU asset
- 1:07 Settings
- 1:32 Enter a lease
- 2:17 Interest and depreciation
- 2:42 IFRS 16 vs ASC 842
- 3:18 Roll-forward and current portion
- 3:43 Maturity analysis and disclosures
- 4:15 Journal entries
- 4:33 Dashboard and checks
- 4:57 Real cases
- 5:36 Recap
What is inside this lease schedule template
| Sheet | What it does | Do you type here? |
|---|---|---|
| Start Here | How the file works, notes on each method and the colour key. | No |
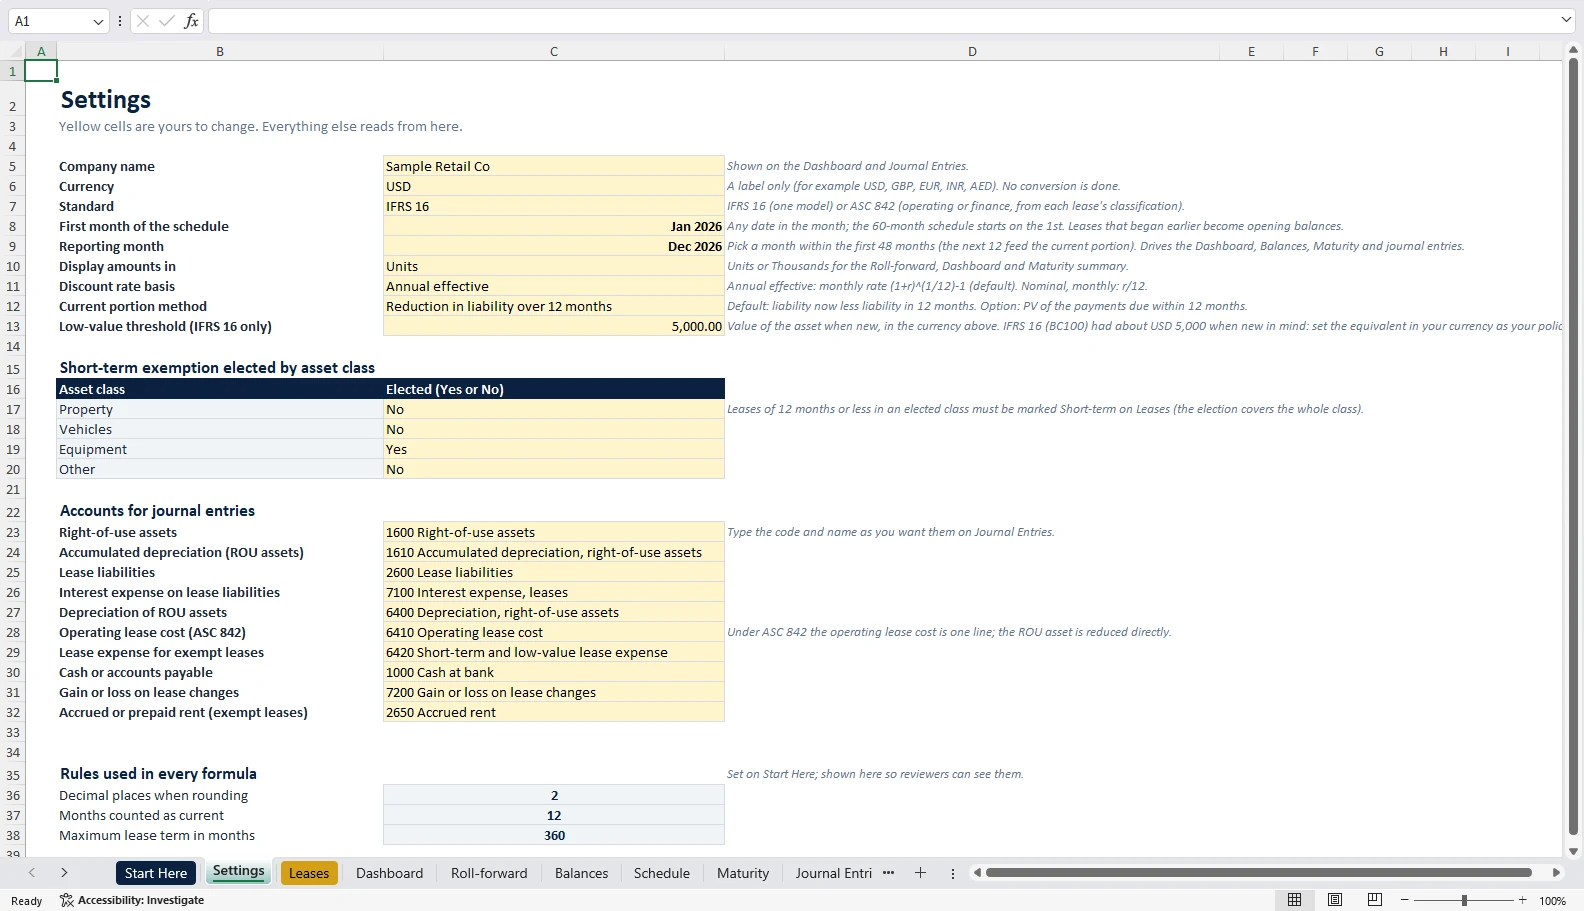
| Settings | Company, currency label, standard, first and reporting month, units, discount rate basis, current portion method, exemption elections and journal accounts. | Yes |
| Leases | One row per lease, up to 50: dates, term, payments, escalation, rent-free months, rate, costs, incentives, classification, exemption and changes. Grey columns show the initial liability and ROU asset, the reporting month balances and a Row check. | Yellow cells only |
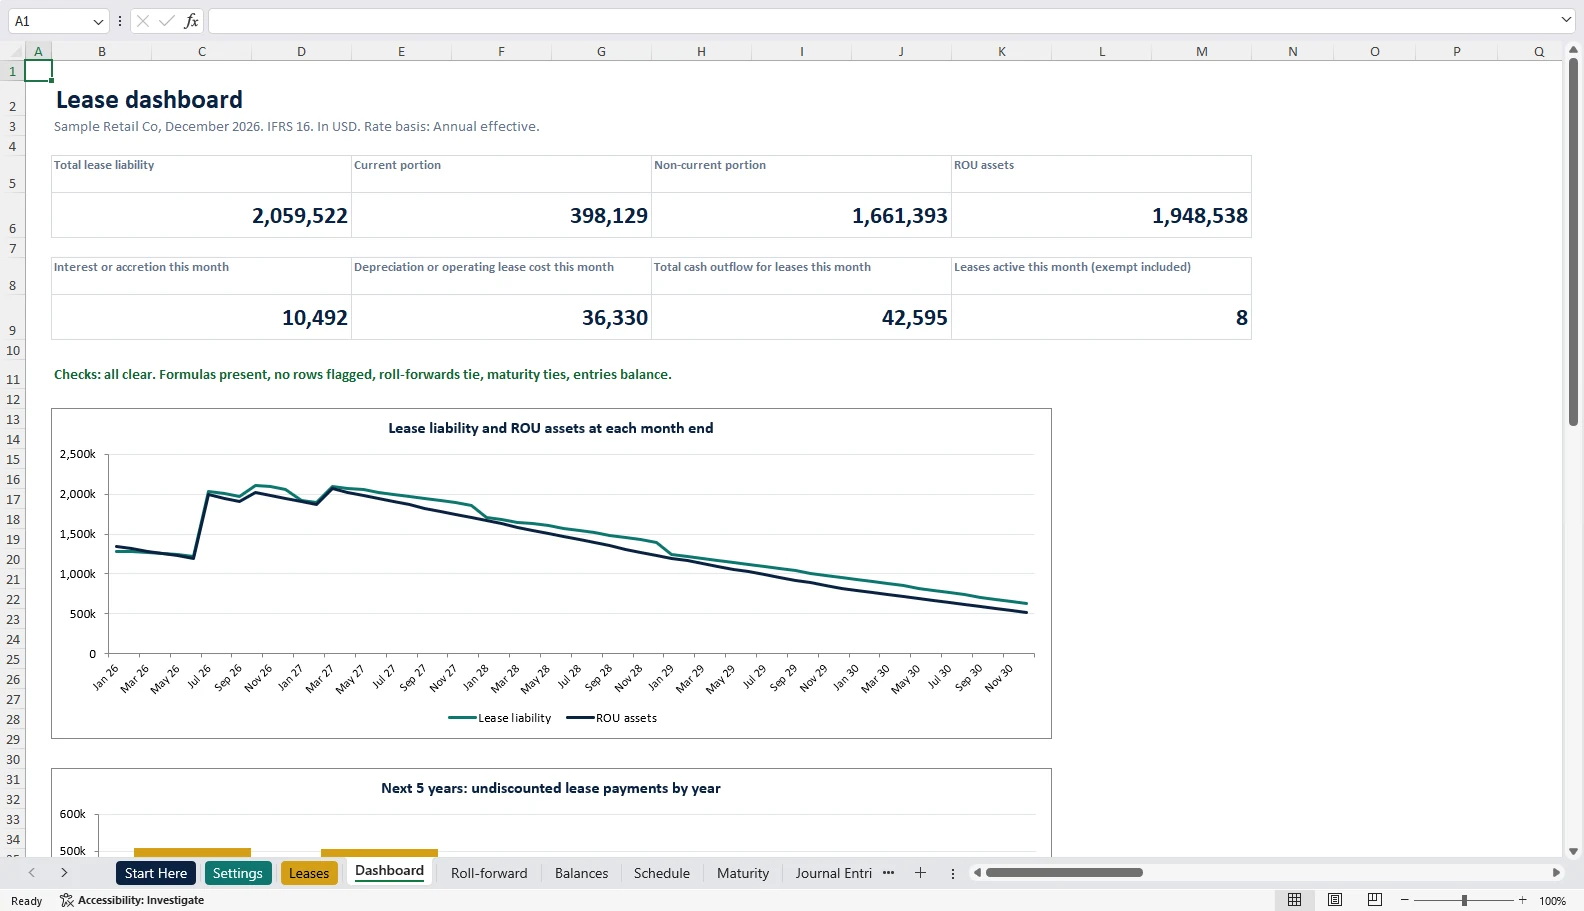
| Dashboard | Headline numbers, two charts and one status line for every check. | No |
| Roll-forward | 60 months of liability and ROU movements, the current split, profit or loss lines and cash flows. | No |
| Balances | Every lease at the reporting month, and at every month end. | No |
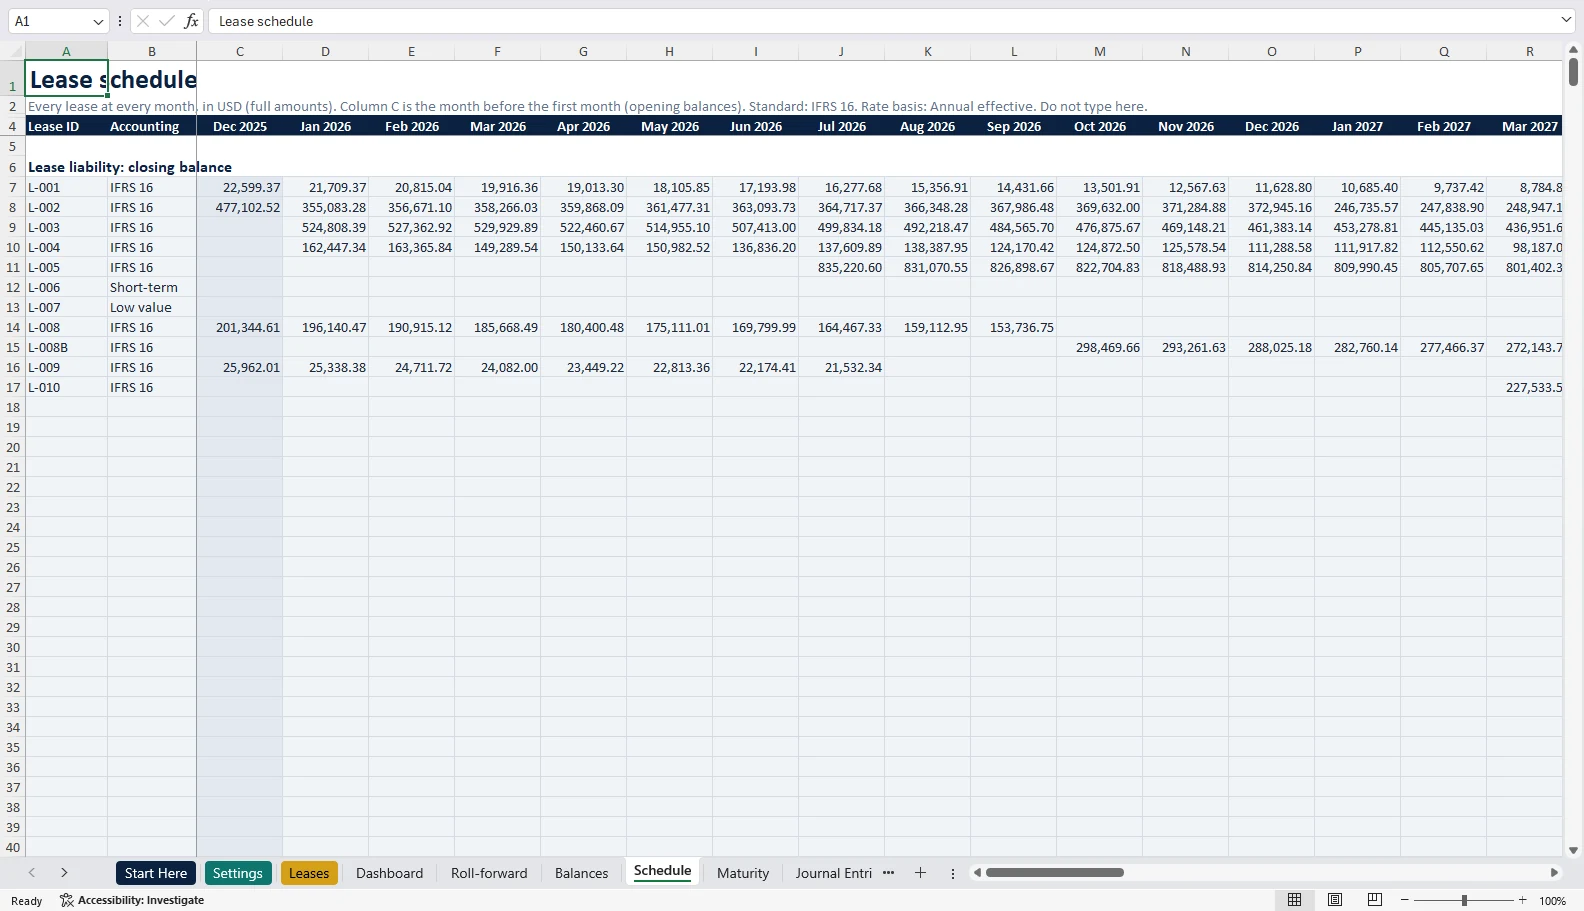
| Schedule | Monthly detail per lease: interest, payments, depreciation, operating lease cost and more. | No |
| Maturity | Undiscounted payments by year, imputed interest, weighted averages and leases not yet started. | No |
| Journal Entries | The entries for the reporting month, debits equal to credits. | No |
| Payments | The payment grid for every lease, months 0 to 360. | No |
What is a lease schedule? IFRS 16 and ASC 842 in plain words
A lease schedule, often called a lease amortization schedule, tracks two balances for each lease. The lease liability is what you still owe, discounted to today. The right of use asset is your right to use the shop, car or machine for the lease term.
Day one is the same under both standards. The liability is the present value of the payments not yet paid, at the rate implicit in the lease or, failing that, your incremental borrowing rate (IBR). The ROU asset is that liability plus payments at or before commencement and initial direct costs, less incentives received.
After day one the standards split. IFRS 16 has one model: interest plus straight-line depreciation, so expense is higher in the early years. ASC 842 classifies each lease as finance, which works like IFRS 16, or operating, which shows one straight-line lease cost with both balances still on the balance sheet.
The official texts are the IFRS 16 Leases page of the IFRS Foundation and FASB ASU 2016-02, Leases (Topic 842).
Lease schedule template worked example: lease liability and ROU asset calculation
The clearest sample lease is L-003, a retail store. It starts in the first month of the schedule and has the features that trip up hand-built schedules: rent-free months, a yearly increase, an incentive and initial direct costs.
| Input | L-003 retail store |
|---|---|
| Commencement | 1 January 2026 |
| Term | 60 months |
| Payment | $10,000.00 a month, in advance |
| Escalation | 3% a year, on each lease anniversary |
| Rent-free months | 3 |
| Discount rate (IBR) | 6% a year, annual effective |
| Initial direct costs | $3,000.00 |
| Incentive received at commencement | $15,000.00 |
| ASC 842 classification | Operating |
Step 1: the payments
Rent-free months set the first 3 payments to zero, and the escalation steps the payment up on each anniversary.
| Lease months | Monthly payment |
|---|---|
| 1 to 3 | 0.00 |
| 4 to 12 | 10,000.00 |
| 13 to 24 | 10,300.00 |
| 25 to 36 | 10,609.00 |
| 37 to 48 | 10,927.27 |
| 49 to 60 | 11,255.09 |
| Total paid | 607,096.32 |
Step 2: the lease liability
The liability is the present value of every payment not made at commencement. The template turns the 6% annual rate into a monthly rate of 0.4867551% and discounts each payment by the months until it is due:
Monthly rate = (1 + 6%)^(1/12) - 1 = 0.4867551%Lease liability = sum of payment(t) / (1 + monthly rate)^t = 522,266.24Nothing is paid at commencement, so all 607,096.32 of payments sit in the liability at their present value. The difference, 84,830.08, is the interest over the 60 months.
Step 3: the right-of-use asset
ROU asset = 522,266.24 + 0.00 paid at commencement + 3,000.00 initial direct costs - 15,000.00 incentive = 510,266.24Step 4: the first months under IFRS 16 (and an ASC 842 finance lease)
| Lease month | Payment | Interest | Closing liability | Depreciation | Closing ROU asset |
|---|---|---|---|---|---|
| 1 (Jan 2026) | 0.00 | 2,542.15 | 524,808.39 | 8,504.44 | 501,761.80 |
| 3 (Mar 2026) | 0.00 | 2,566.97 | 529,929.89 | 8,504.44 | 484,752.93 |
| 4 (Apr 2026) | 10,000.00 | 2,530.78 | 522,460.67 | 8,504.44 | 476,248.49 |
| 12 (Dec 2026) | 10,000.00 | 2,234.93 | 461,383.14 | 8,504.44 | 408,212.99 |
| 13 (Jan 2027) | 10,300.00 | 2,195.67 | 453,278.81 | 8,504.44 | 399,708.55 |
Interest accrues every month, rent-free months included, so the liability grows until the first payment in month 4. Depreciation is 510,266.24 over 60 months, and cent differences are absorbed so the asset ends at exactly 0.00.
Step 5: the same lease as an ASC 842 operating lease
Total lease cost is 607,096.32 of payments + 3,000.00 of costs less the 15,000.00 incentive = 595,096.32, or 9,918.272 a month. The liability is identical; the ROU asset falls by the straight-line cost less the accretion.
| Lease month | Accretion | Closing liability | Straight-line cost | ROU reduction | Closing ROU asset |
|---|---|---|---|---|---|
| 1 (Jan 2026) | 2,542.15 | 524,808.39 | 9,918.27 | 7,376.12 | 502,890.12 |
| 3 (Mar 2026) | 2,566.97 | 529,929.89 | 9,918.28 | 7,351.31 | 488,175.07 |
| 4 (Apr 2026) | 2,530.78 | 522,460.67 | 9,918.27 | 7,387.49 | 480,787.58 |
| 12 (Dec 2026) | 2,234.93 | 461,383.14 | 9,918.27 | 7,683.34 | 420,363.88 |
| 13 (Jan 2027) | 2,195.67 | 453,278.81 | 9,918.28 | 7,722.61 | 412,641.27 |
Step 6: balances at the reporting month
At 31 December 2026, the sample’s reporting month, L-003 has a lease liability of 461,383.14: 99,898.26 current and 361,484.88 non-current. The ROU asset is 408,212.99 under IFRS 16 and 420,363.88 under ASC 842 operating.
Step 7: the journal entries
| When | Account | Debit | Credit |
|---|---|---|---|
| Day 1 | Right-of-use asset | 510,266.24 | |
| Day 1 | Lease liability | 522,266.24 | |
| Day 1 | Cash: costs paid | 3,000.00 | |
| Day 1 | Cash: incentive received | 15,000.00 | |
| Dec, IFRS | Interest expense | 2,234.93 | |
| Dec, IFRS | Lease liability | 2,234.93 | |
| Dec, IFRS | Lease liability | 10,000.00 | |
| Dec, IFRS | Cash | 10,000.00 | |
| Dec, IFRS | Depreciation expense | 8,504.44 | |
| Dec, IFRS | Accumulated depreciation | 8,504.44 | |
| Dec, ASC | Operating lease cost | 9,918.27 | |
| Dec, ASC | Lease liability (accretion) | 2,234.93 | |
| Dec, ASC | ROU asset | 7,683.34 | |
| Dec, ASC | Lease liability | 10,000.00 | |
| Dec, ASC | Cash | 10,000.00 |
Step 8: same total expense, different timing
| Year | Interest | Depreciation | IFRS 16 total | ASC 842 operating cost | Cash paid |
|---|---|---|---|---|---|
| 2026 | 29,116.90 | 102,053.25 | 131,170.15 | 119,019.26 | 90,000.00 |
| 2027 | 23,701.74 | 102,053.25 | 125,754.99 | 119,019.27 | 123,600.00 |
| 2028 | 17,588.42 | 102,053.24 | 119,641.66 | 119,019.26 | 127,308.00 |
| 2029 | 10,882.21 | 102,053.25 | 112,935.46 | 119,019.27 | 131,127.24 |
| 2030 | 3,540.81 | 102,053.25 | 105,594.06 | 119,019.26 | 135,061.08 |
| Total | 84,830.08 | 510,266.24 | 595,096.32 | 595,096.32 | 607,096.32 |
Both models expense 595,096.32 in total, but IFRS 16 front-loads it.
How to use the lease schedule template, sheet by sheet
- Settings. Type your company name and currency label. Pick IFRS 16 or ASC 842, the first month of the 60-month schedule and the reporting month, within the first 48 months so the next 12 exist for the current split.
- Policies. Check the discount rate basis, the current portion method, the short-term election by asset class, the low-value threshold and the journal accounts.
- Leases. Type over the sample rows, delete them as whole rows, or insert whole rows above Totals. Fill the yellow cells only, up to 50 leases. Enter the term in whole months, up to 360. Under ASC 842, pick Operating or Finance; the template does not test the criteria.
- Exemptions. Mark a lease Short-term or Low value. Low value needs the value when new and applies under IFRS 16 only.
- Row check. Every row should say OK or show a blue note. Red means fix the row; amber means check it.
- Roll-forward and Balances. Read the closing balances, the current split and the check lines, then tie the totals to your ledger.
- Maturity. At year end, take the maturity table and weighted averages for your lease note.
- Journal Entries. Post the month’s entries. The Dashboard status line should say all clear. Change the reporting month for the next close.
Lease liability and right-of-use asset roll-forward
Closing liability = opening + new leases + interest - payments + remeasurements - terminationsClosing ROU asset = opening + new leases - depreciation + remeasurements - terminationsHere are the 12 months to Dec 2026 for all the sample leases under IFRS 16, from the first column of the Roll-forward sheet, which totals the 12 months to the reporting month (Jan 2026 to Dec 2026):
| Line | Lease liability | ROU asset |
|---|---|---|
| Opening, 1 January 2026 | 727,008.51 | 701,971.67 |
| New leases | 1,514,649.17 | 1,512,149.17 |
| Interest | 97,233.69 | |
| Payments | (407,750.00) | |
| Depreciation | (394,806.32) | |
| Remeasurements and modifications | 149,912.67 | 149,912.67 |
| Terminations | (21,532.34) | (20,688.97) |
| Closing, 31 December 2026 | 2,059,521.70 | 1,948,538.22 |
| Of which current | 398,128.73 | |
| Of which non-current | 1,661,392.97 |
New leases differ by 2,500.00 between the columns because the ROU asset adds costs and instalments paid at commencement and deducts incentives. Of the 407,750.00 paid, 312,953.53 was principal and 94,796.47 interest, the split you need for the cash flow statement.
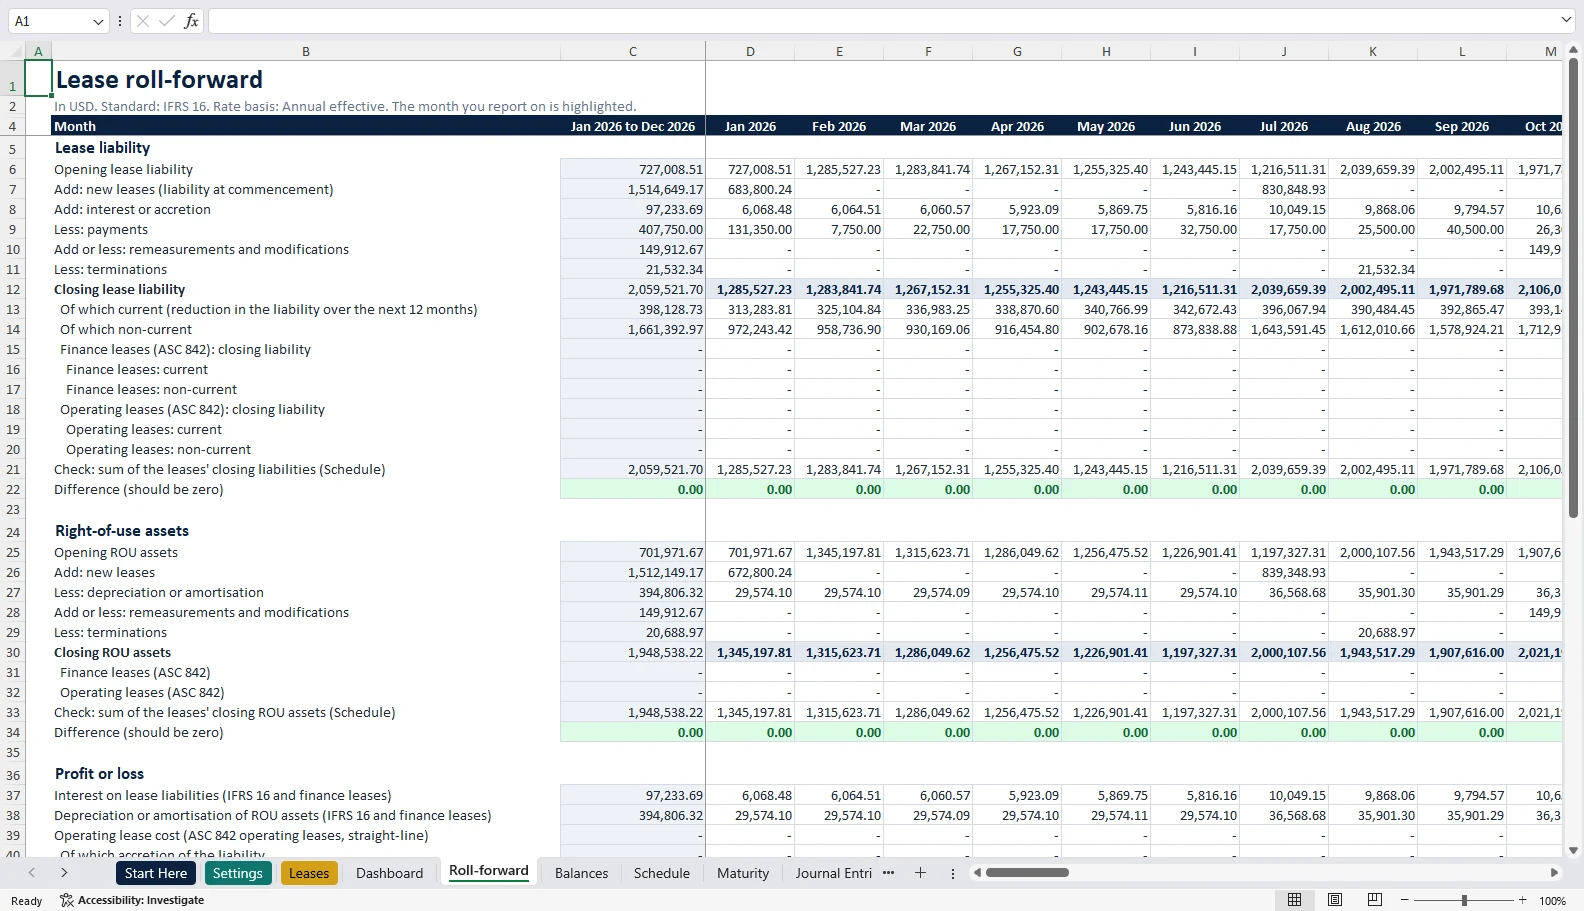
Current vs non-current lease liability
The default current portion is the reduction in the liability over the next 12 months: the liability now less the liability 12 months later. For L-003 that is 461,383.14 less 361,484.88, or 99,898.26. Never use next year’s undiscounted payments, 123,600.00 here, because they include future interest.
The option on Settings is the present value of the payments due within 12 months, which gives 120,359.66 for L-003. It suits leases paid yearly or quarterly in advance: for L-002, the head office, the default gives 113,797.96 although 127,308.00 is due on 1 January 2027, and the option gives 127,308.00. Pick one policy and keep it.
The ROU asset is not split; it is non-current. IAS 1 sets the current test under IFRS, and ASC 842 classifies lease liabilities like other financial liabilities.
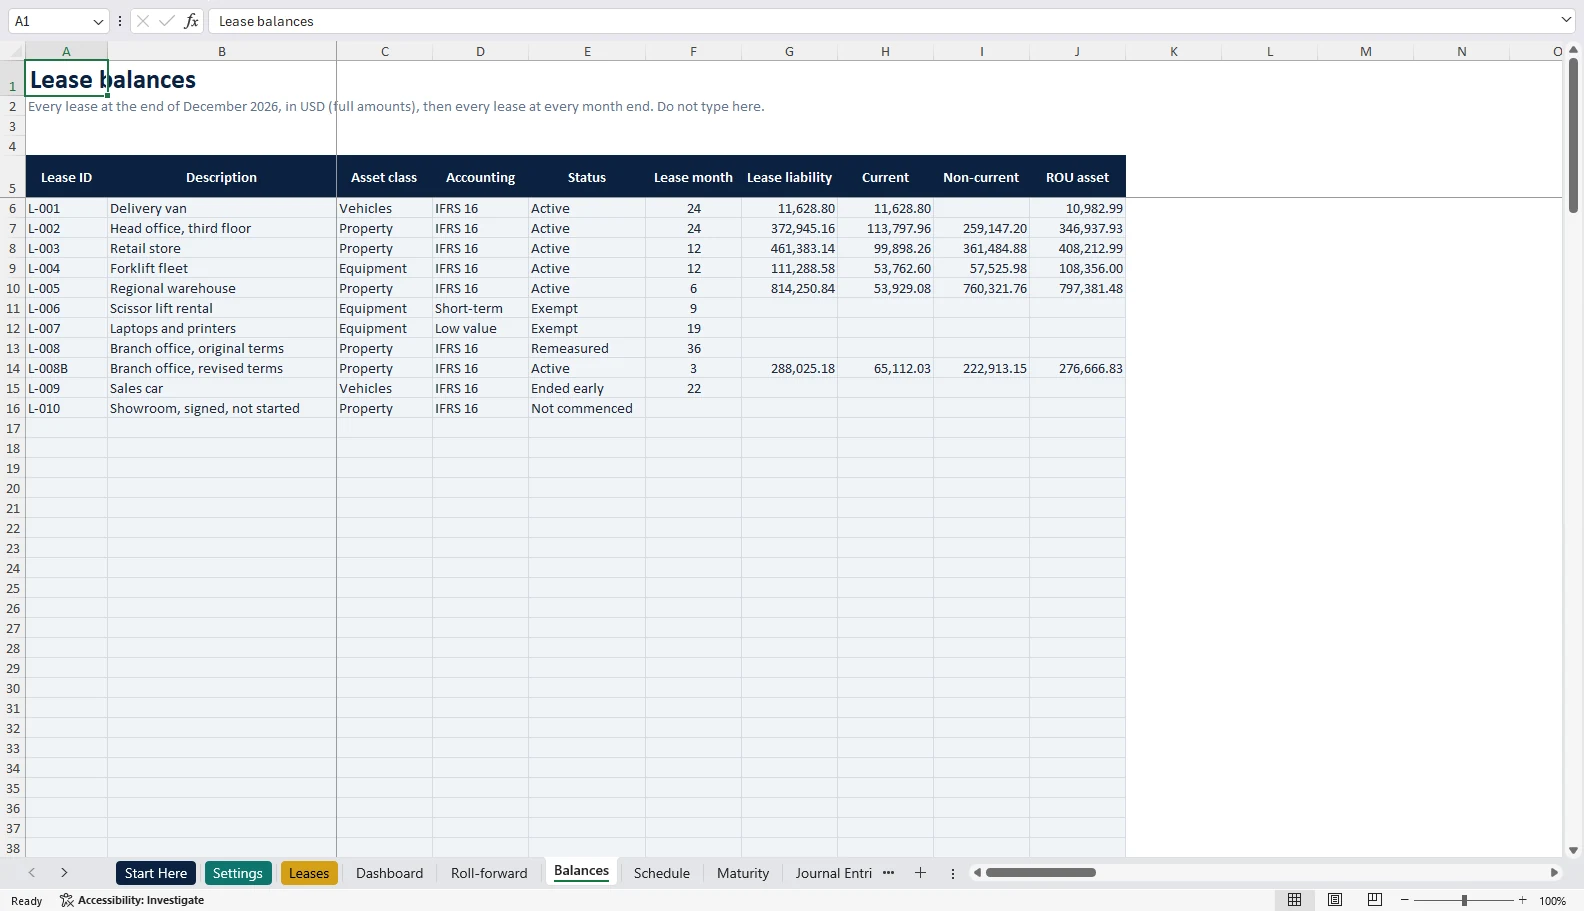
IFRS 16 vs ASC 842: differences that change the numbers
| Topic | IFRS 16 | ASC 842 |
|---|---|---|
| Lessee model | One model for every lease on the balance sheet | Finance or operating, from the classification you enter |
| Profit or loss | Interest plus straight-line depreciation, front-loaded | Finance: interest plus amortisation. Operating: one straight-line lease cost |
| L-003 expense in 2026 | 131,170.15 | 119,019.26 |
| L-003 ROU asset at Dec 2026 | 408,212.99 | 420,363.88 |
| Low-value exemption | Lease by lease, value when new (about USD 5,000); never cars | None; a capitalisation threshold can be a policy |
| Short-term exemption | 12 months or less; any purchase option rules it out | 12 months or less; a purchase option reasonably certain to be exercised rules it out |
| Discount rate | Implicit rate, otherwise the IBR | The same, plus a risk-free election for non-public companies |
| Index-linked rent changes | Remeasure at the unchanged rate | No remeasurement; the increase is a variable cost |
| Principal paid | Financing cash flow | Finance: financing. Operating: operating |
| Maturity analysis | IFRS 7 approach, bands you choose | Each of the next five years plus thereafter, finance and operating separately |
Switch the Standard on Settings and the whole workbook follows: under ASC 842 the Roll-forward, Maturity and Journal Entries show finance and operating leases on separate lines.
Choosing the discount rate: annual effective or nominal
Use the rate implicit in the lease if it is readily determinable. Most lessees cannot work it out, so they use their incremental borrowing rate: the cost of borrowing over a similar term, with similar security. Document how you built it.
Under ASC 842, companies that are not public business entities may elect a risk-free rate by asset class (FASB ASU 2021-09), but must still use the implicit rate when it is readily determinable. IFRS 16 has no risk-free option.
The convention matters as much as the rate. A 6% IBR read as an annual effective rate is not 6% nominal compounded monthly, so the template asks which one you mean:
Annual effective (default): monthly rate = (1 + r)^(1/12) - 1, so 6% gives 0.4867551%Nominal, monthly: monthly rate = r / 12, so 6% gives 0.5000000%The default reads the IBR as an annual rate, so monthly interest compounds to exactly that rate: L-002’s first-year interest of 24,872.64 is exactly 5.5% of its 452,229.88 opening liability. Pick Nominal, monthly when your rate is quoted that way, or to match a PV(rate/12) check.
| Rate on L-003 | Liability, annual effective | Liability, nominal monthly | ROU asset, annual effective |
|---|---|---|---|
| 4% | 548,220.82 | 547,220.07 | 536,220.82 |
| 5% | 534,978.85 | 533,475.14 | 522,978.85 |
| 6% | 522,266.24 | 520,183.19 | 510,266.24 |
| 7% | 510,055.61 | 507,327.20 | 498,055.61 |
| 8% | 498,321.31 | 494,890.83 | 486,321.31 |
Short-term and low-value lease exemptions
A short-term lease has a term of 12 months or less at commencement. You elect the exemption by class of asset on Settings, and both standards allow it. Low value is an IFRS 16 option, taken lease by lease, judged on the value of the asset when new. ASC 842 has no low-value exemption.
In the sample, L-006 is a 9-month scissor lift rental at $1,200.00 a month in the Equipment class, which is elected on Settings: 10,800.00 of straight-line expense in 2026 and no liability or ROU asset. L-007 is laptops and printers at $95.00 a month, worth $3,000 when new: 1,140.00 of expense in 2026.
Exempt leases stay out of the maturity analysis and weighted averages. Switch the sample to ASC 842 and L-007 shows a red Row check, because it must then be capitalised: set Exempt to No and add a rate.
Real cases: escalations, payments in advance, remeasurements and early ends
Fixed escalations and index-linked rent
L-005 is a 10-year warehouse at $8,500.00 a month in advance, rising 2.5% a year to 8,712.50 and then 8,930.31. Its liability starts at 830,848.93, and the ROU asset at 839,348.93 includes the first instalment paid on day one. Rent linked to an index such as CPI goes in at the index at commencement with 0% escalation. When the index moves, IFRS 16 remeasures with a continuation row at the original rate; ASC 842 does not, and the increase is a variable cost.
Payments in advance
L-002, the head office, pays its rent once a year, each January: $120,000 in the first year, rising 3% a year. The first instalment is paid at commencement, so it goes into the ROU asset, not the liability: 452,229.88 + 120,000.00 + 6,000.00 of costs = 578,229.88. Do not repeat it in Other payments; Row check warns you if you do.
Leases that started before the schedule
L-001 and L-002 began on 1 January 2025, a year before the schedule. Each is valued from commencement, so the opening balances are exact: L-001 22,599.37 liability and 21,965.97 ROU asset; L-002 477,102.52 and 462,583.90. Start Here explains how to enter leases brought in on transition reliefs.
Remeasurements and modifications: the continuation row
From 1 October 2026, the L-008 office rent rises from $6,000 to $6,800 and the lease is extended, at a new rate of 6.75%. On L-008 you type that date in Remeasured or ended on. L-008B is a new row from the same date with 51 months, the new payment and rate, and L-008 in Continues lease ID.
The old liability of 153,736.75 becomes 303,649.42. Under IFRS 16 the ROU asset sat 9,690.91 below the liability, and that carry-over moves across, so the ROU asset goes from 144,045.84 to 293,958.51. Both move by 149,912.67 on the remeasurement line. Under ASC 842 operating the new straight-line cost is 6,800.00 a month.
Early termination
L-009, a sales car, is returned on 1 August 2026 with a $1,500 fee. The template takes off the 21,532.34 liability and the 20,688.97 ROU asset; liability less asset less fee is a loss of 656.63.
Signed, not started: L-010 starts on 1 March 2027, after the reporting month, so it stays off the balance sheet. Maturity lists it separately with 267,580.44 of undiscounted payments.
Maturity analysis of lease liabilities
The Maturity sheet lists the undiscounted payments still in the liability, by year, and reconciles them to the balance sheet. Here is Dec 2026 for the sample under IFRS 16:
| Due | Undiscounted payments |
|---|---|
| Within 1 year | 507,783.00 |
| 1 to 2 years | 505,892.10 |
| 2 to 3 years | 456,291.58 |
| 3 to 4 years | 327,876.96 |
| 4 to 5 years | 113,996.28 |
| Later than 5 years | 548,897.58 |
| Total undiscounted payments | 2,460,737.50 |
| Less imputed interest | (401,215.80) |
| Lease liability | 2,059,521.70 |
These are the five years plus thereafter that ASC 842 asks for, and they work as IFRS 7 time bands too. Under ASC 842 the same sample splits into finance leases, 132,000.00 less 9,082.62 = 122,917.38, and operating leases, 2,328,737.50 less 392,133.18 = 1,936,604.32.
The weighted-average remaining lease term is 5.87 years and the weighted-average discount rate 6.29%; under ASC 842, 1.91 years and 6.91% for finance leases, 6.12 years and 6.26% for operating leases.
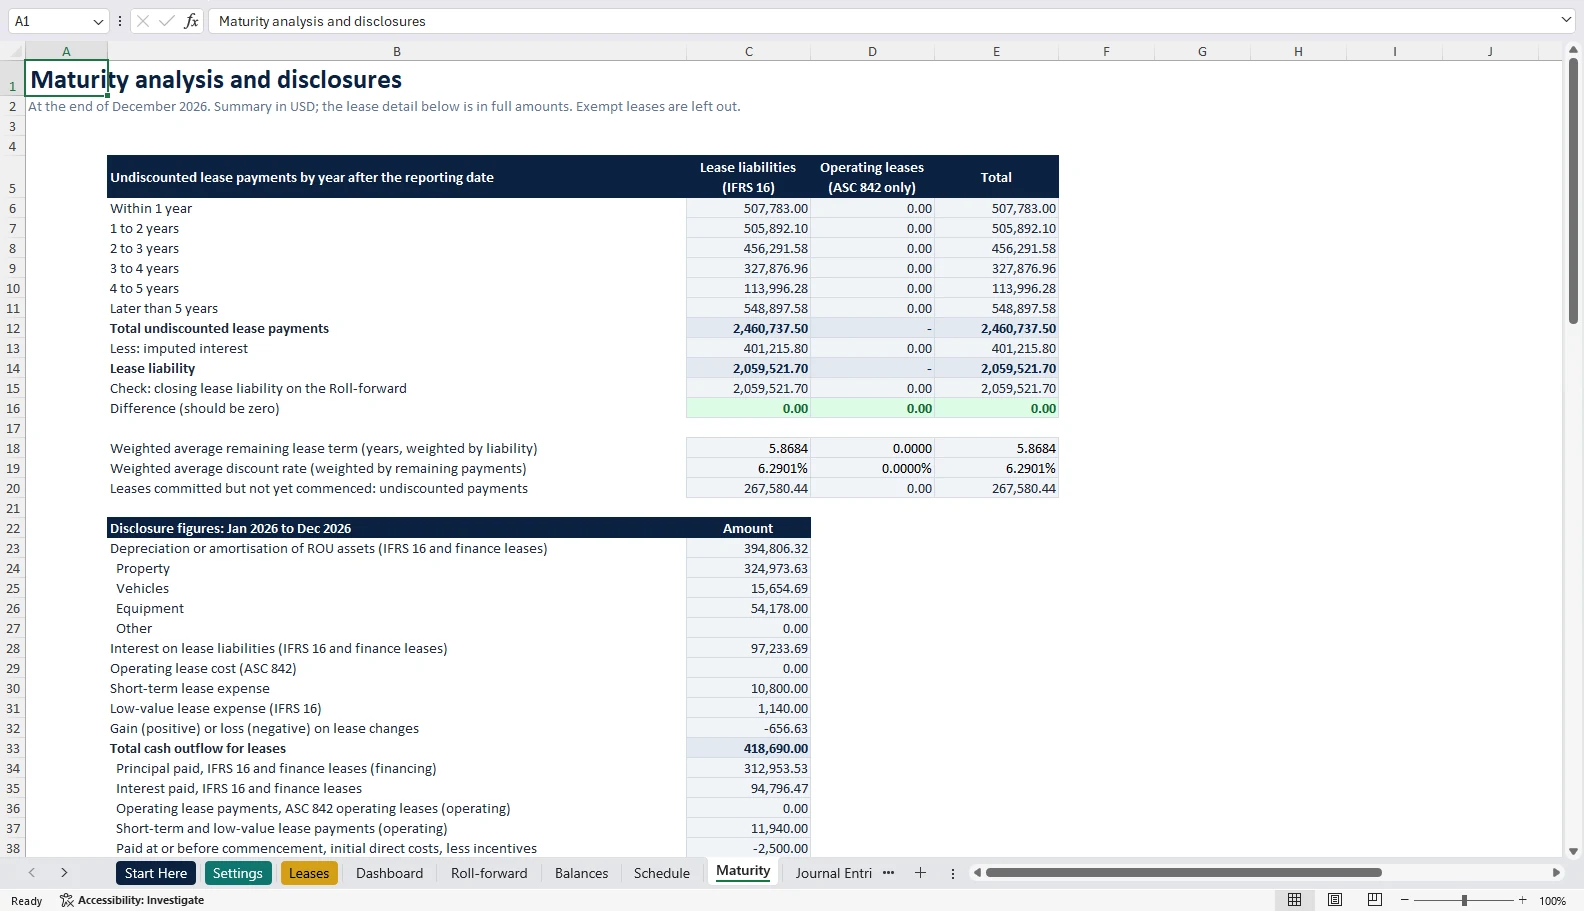
Lease journal entries for any month
Journal Entries gives eight entries for the reporting month: new leases, interest, payments, depreciation, ASC 842 operating cost, exempt leases, remeasurements and early ends. Here is Dec 2026 under IFRS 16:
| Entry | Account | Debit | Credit |
|---|---|---|---|
| 2 | 7100 Interest expense, leases | 10,491.88 | |
| 2 | 2600 Lease liabilities | 10,491.88 | |
| 3 | 2600 Lease liabilities | 41,300.00 | |
| 3 | 1000 Cash at bank | 41,300.00 | |
| 4 | 6400 Depreciation, right-of-use assets | 36,330.16 | |
| 4 | 1610 Accumulated depreciation, right-of-use assets | 36,330.16 | |
| 6 | 6420 Short-term and low-value lease expense | 1,295.00 | |
| 6 | 1000 Cash at bank | 1,295.00 | |
| Totals | 89,417.04 | 89,417.04 |
Account names come from Settings, so the entries read like your chart of accounts.
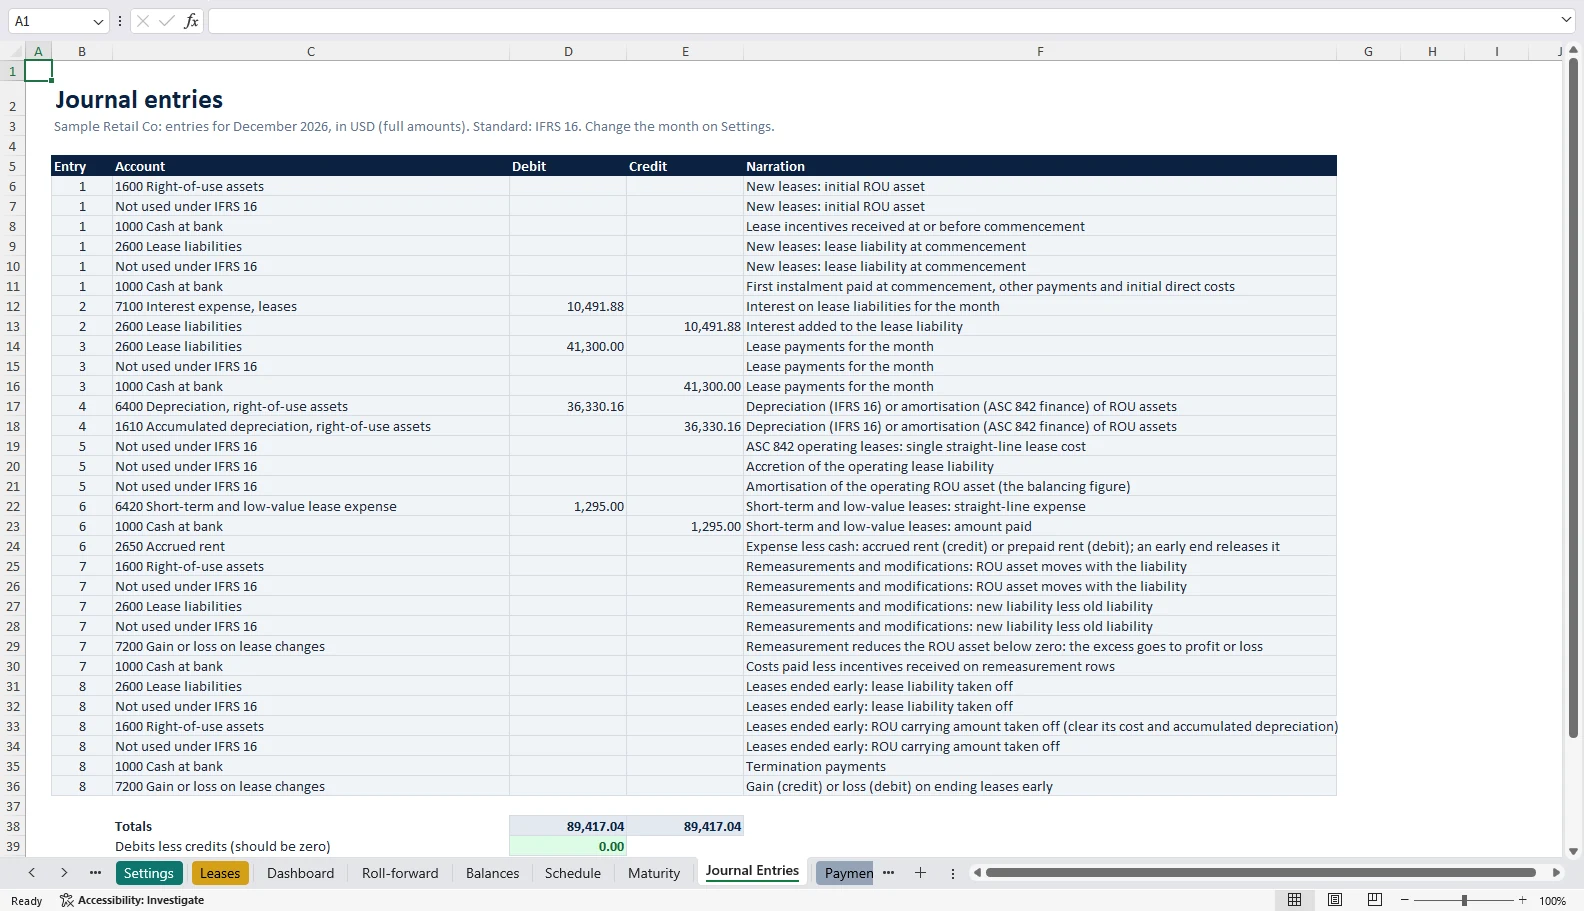
Checks that tell you when something does not tie
The Dashboard rolls every check into one status line, which reads Checks: all clear when everything holds. Among them:
- Each initial liability agrees to the present value of its payments.
- Every liability and ROU asset ends at exactly zero and never goes negative.
- Both roll-forwards and the maturity analysis tie to the leases.
- The journal entries balance, and no grey cell was typed over.
Who this lease schedule template is for, and what it does not do
It suits IFRS 16 and ASC 842 lessees with up to 50 leases, the accountants and auditors who review them, and students learning lease accounting. If you also run accruals, our prepaid expense schedule template and deferred revenue schedule template use the same layout, and the accounts payable template tracks the rent invoices themselves.
It does not cover variable payments, purchase options reasonably certain to be exercised, residual value guarantees, impairment, foreign currency remeasurement, partial terminations, lessor accounting, subleases or sale and leaseback. There is no restoration cost column, and payment patterns beyond a yearly escalation and rent-free months need a continuation row.
Related templates and guides
- Prepaid expense schedule template: costs paid in advance.
- Deferred revenue schedule template: the revenue-side schedule.
- Bank reconciliation template: tie rent payments to the bank.
- Excel financial dashboard template: management reporting.
- Excel formulas for finance: PV, NPV and ROUND.
- MIS report format: the monthly pack lease costs feed into.
- Cash flow decision tool: cash timing.
Please note: standards and their interpretation change, and there can be a gap between a change and our update. Check the standard or your auditor before you act. This template and guide help with working papers; they are not accounting, tax or legal advice, and ReconScribe is not responsible for decisions made on them.
Lease schedule template FAQ
How do you calculate a lease liability in Excel?
Take the present value of the payments not paid at commencement, at the rate implicit in the lease or your incremental borrowing rate. For level monthly payments in arrears, =PV((1+6%)^(1/12)-1,36,-1000) gives 32,948.96, and =PV(6%/12,36,-1000) gives 32,871.02. When payments change, discount each one separately, as the template does on its Payments sheet.
How is the right of use asset calculated?
Start with the initial lease liability, add payments made at or before commencement and initial direct costs, and subtract incentives received. IFRS 16 also adds restoration costs. For the sample store: 522,266.24 + 3,000.00 less 15,000.00 = 510,266.24.
What is the difference between IFRS 16 and ASC 842?
Both put nearly all leases on the balance sheet at the same day-one amounts. IFRS 16 uses one model with interest and depreciation, so expense is front-loaded. ASC 842 has finance leases, which work like IFRS 16, and operating leases with one straight-line cost.
What discount rate should you use for a lease?
The rate implicit in the lease if it is readily determinable; otherwise your incremental borrowing rate for a similar term and security. US companies that are not public business entities may elect a risk-free rate by asset class. State whether the rate is annual effective or nominal.
What counts as a low-value lease under IFRS 16?
The standard sets no number. Its Basis for Conclusions had about USD 5,000 or less when new in mind, such as laptops and phones. It is judged lease by lease on the value when new, and cars never qualify. ASC 842 has no low-value exemption.
How do you split the lease liability into current and non-current?
Take the liability today less the liability expected in 12 months. For the sample store at 31 December 2026, 461,383.14 splits into 99,898.26 current and 361,484.88 non-current. Do not use next year's undiscounted payments, 123,600.00, because they include interest.
What are the journal entries for an ASC 842 operating lease?
At commencement, debit the operating ROU asset and credit the operating lease liability. Each month, debit the straight-line lease cost, credit the liability with the accretion and the ROU asset with the rest: 9,918.27, 2,234.93 and 7,683.34 for the sample store in December 2026. The payment then reduces the liability.
What are the journal entries for a lease under IFRS 16?
At commencement, debit the ROU asset and credit the lease liability. Each month, book interest to the liability, the payment against the liability and straight-line depreciation. For the sample store in December 2026: 2,234.93 of interest and 8,504.44 of depreciation against 10,000.00 of rent.
Can you do IFRS 16 or ASC 842 lease accounting in Excel?
Yes, for a manageable portfolio, if the inputs are documented and the schedule is tied to the ledger every month. This template holds 50 leases over 60 months. Hundreds of leases, frequent changes, variable payments or several currencies call for dedicated software.